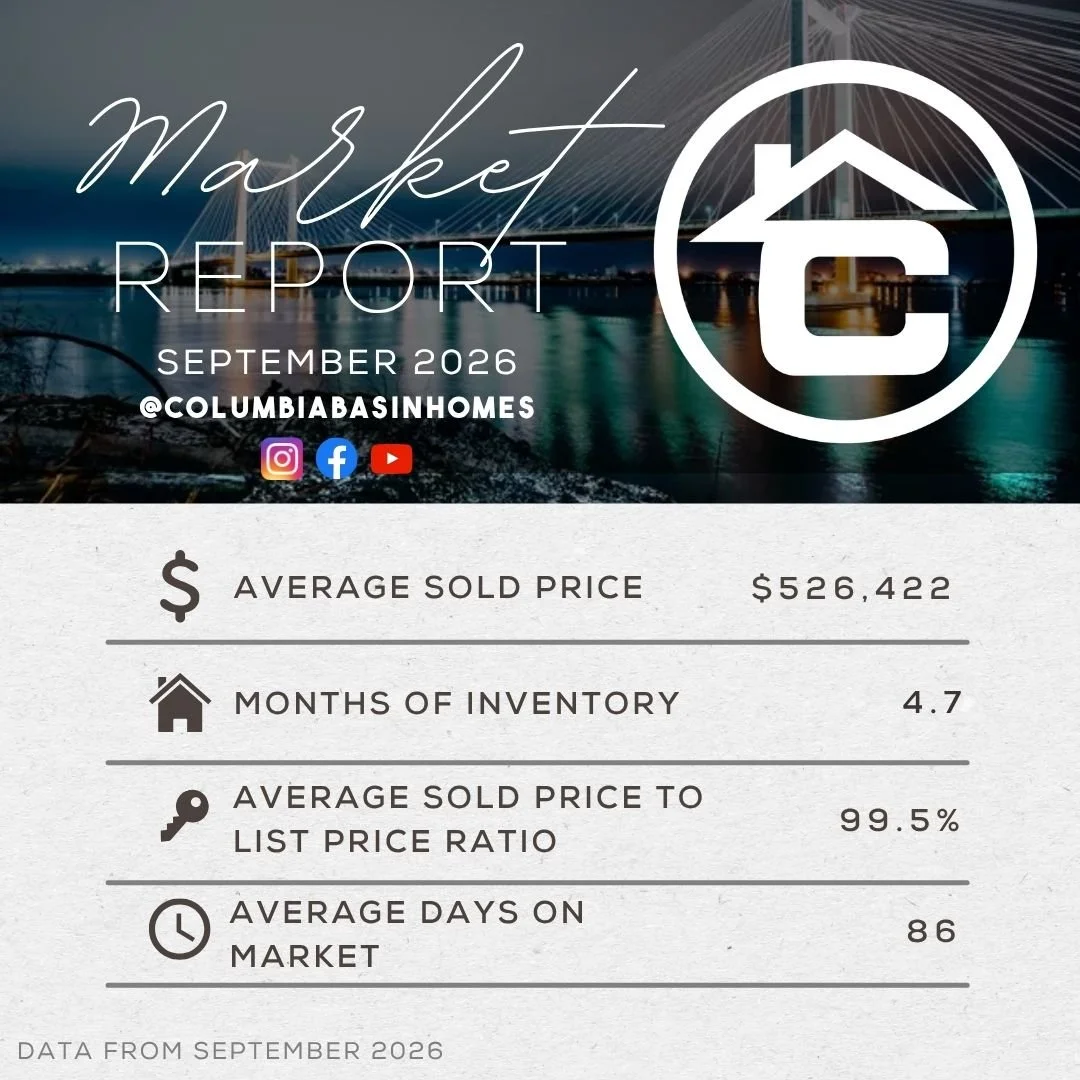
Spokane's real estate market saw new pending sales rise nearly 5% year-over-year at the end of September 2026, even as mortgage rates climbed past 7.5%. Prices remained virtually flat, inching up less than 1% compared to last year. People are still making moves across the Inland Northwest because major life events continue to drive local real estate.
Spokane Home Prices and Inventory Data
Spokane home prices remained remarkably steady at the end of September 2026, showing less than a 1% increase year-over-year. Meanwhile, buyer demand stayed resilient, with new pending sales increasing by almost 5% compared to the same period last year.
Because real estate moves like a slow-moving freight train, prices are holding firm even in a high-rate environment. Buyers are out in the market making moves when life requires it, whether due to marriage, divorce, job changes, or retirement. To get an accurate picture of value right now, look closely at pending and expired listings rather than sold data from six months ago, when rates were sitting closer to 6%. If you want to see where your property fits, check our Home Valuation page.
Rate Context and Economic Pressures
Mortgage rates ended September 2026 above 7.5%, hitting their highest levels since late 2023. You would have to look back to the early 2000s to find a prolonged stretch of borrowing costs at these levels.
A combination of factors is keeping upward pressure on rates. The 10-year Treasury yield recently crossed 5.3%, crude oil remained elevated over $100 a barrel, and massive borrowing from both the U.S. government—running a $2 trillion annual deficit—and major tech companies expanding AI infrastructure is driving up capital costs worldwide. Elevated borrowing costs may remain the new normal for the next 6 to 12 months, making creative financing tools far more important than simple price chops.
Strategic Advice for Sellers
Sellers in Spokane can net more money by offering rate buydown concessions rather than making traditional list price reductions. A seller contribution that buys down a buyer's interest rate makes a house significantly more affordable on a monthly basis while protecting the overall sale price.
For example, on a $450,000 purchase, a $20,000 to $30,000 builder or seller concession can lower a buyer's monthly payment to match what a $350,000 home would cost at standard 6.5% or 7.5% rates. That makes your home stand out immediately to active buyers who care far more about their monthly outlay than the top-line sticker price.
Creative Financing Advice for Buyers
Buyers can secure effective starting interest rates as low as 4.625% or 4.99% using temporary buydowns, adjustable-rate mortgages (ARMs), or builder incentives. You do not have to accept the standard 7.5% benchmark rate as your only option.
A 3-2-1 temporary buydown lowers your interest rate by 3% in year one, 2% in year two, and 1% in year three, saving nearly $800 a month in that first year. The seller-funded buydown money sits in an escrow account, so if interest rates drop and you refinance early, the leftover funds go directly toward reducing your loan principal balance. Additionally, today's 7-year or 10-year ARMs operate under strict Dodd-Frank underwriting guidelines, offering significantly lower fixed rates during your initial years without the risks of the mid-2000s. Compare this strategy with last month's trends in our previous month's Spokane market update.
Looking to buy or sell? Visit spokanehomeguy.com or call 509-990-SOLD (7653) for real estate or 509-747-1300 for mortgage options to get started!
More monthly updates: Previous month's Spokane market update ← August 2026 Spokane market update